Let’s be honest: saving money is difficult when your income barely covers your expenses. Between food, rent, transportation, bills, and unexpected costs, there may be very little left at the end of the month.
If you are in this situation, being told to save more or stop buying things you enjoy can feel frustrating. Sometimes, the problem is not poor spending habits. Your income simply may not be enough to cover everything comfortably.
However, there are practical ways to manage your money better, reduce unnecessary expenses, and create a little breathing room, even when your budget is tight.
In this guide, you will learn how to save money when your income is not enough, without relying on unrealistic budgeting rules or making your life unnecessarily difficult.
1. Start With a Realistic Budget
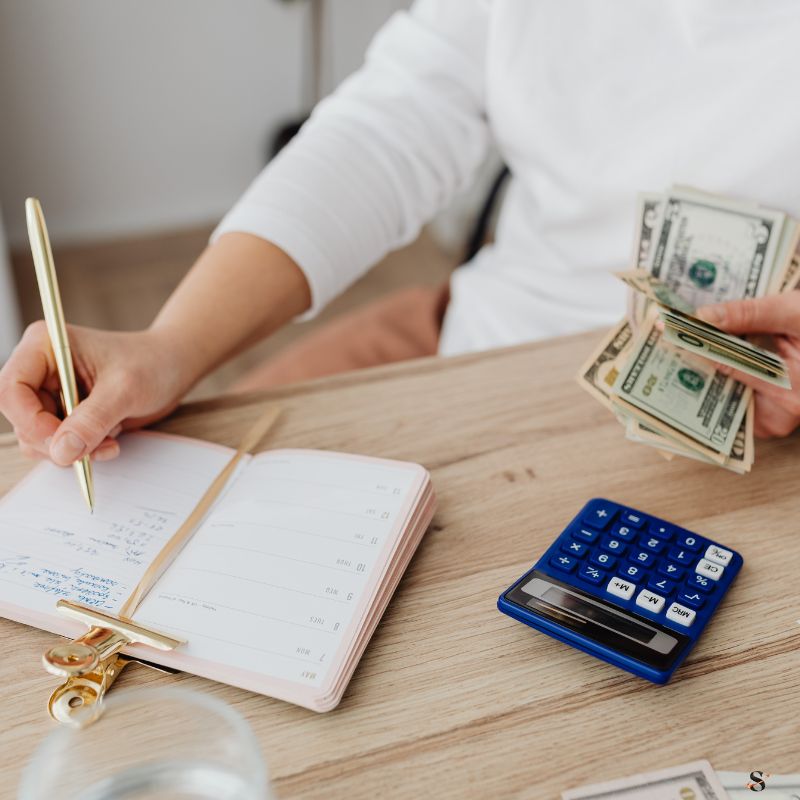
Before you can change your spending habits, you need to understand where your money goes.
A budget does not have to be complicated. You can use a notebook, a spreadsheet, or a free budgeting app to record your income and expenses.
Start by writing down:
- Your total monthly income.
- Essential expenses, such as rent, food, transportation, and utilities.
- Debt repayments and other financial commitments.
- Non-essential spending, including subscriptions and impulse purchases.
Subtract your expenses from your income. If you are spending more than you earn, identify the biggest gaps first.
You may have heard of the 50/30/20 budgeting rule, which allocates 50% of income to needs, 30% to wants, and 20% to savings. While this can be a useful starting point, it may not work when essential expenses already consume most of your income.
Adjust your budget to reflect your actual circumstances. The goal is to understand your money and make informed decisions, not to follow percentages that do not fit your life.
2. Separate Your Needs From Your Wants
When money is tight, prioritizing becomes important.
Essential expenses generally include housing, basic food, necessary transportation, utilities, healthcare, and minimum debt payments. Other expenses may be flexible, depending on your circumstances.
Review your spending and ask yourself three questions:
- Do I genuinely need this right now?
- Is there a cheaper alternative that works just as well?
- Can I postpone this expense without creating a bigger problem later?
For example, you might switch to a less expensive data plan, prepare more meals at home, or delay buying new clothes when you already have suitable options.
The aim is not to eliminate every enjoyable thing from your life. It is to identify expenses you can reduce without compromising your health, safety, or essential needs.
3. Reduce Small Expenses That Add Up
Some expenses seem insignificant on their own but become substantial over time.
Look for opportunities to reduce spending in these areas:
Subscriptions: Cancel services you rarely use and review recurring payments regularly.
Food: Plan meals before shopping, use ingredients you already have, and reduce food waste.
Transportation: Where practical and safe, compare transport options, combine errands, or share journeys.
Impulse purchases: Wait 24 hours before buying non-essential items. This gives you time to decide whether the purchase is worthwhile.
Utilities and data: Review your electricity usage, phone plans, and internet packages to see whether a cheaper option meets your needs.
You do not need to cut everything at once. Choose two expenses you can realistically reduce this month and review the results.
4. Save Small Amounts When You Can
One common mistake is believing that saving only counts when you can put away a large amount.
If your budget allows it, start with a small amount you can manage consistently. This could be a modest weekly contribution or a little money left over after essential expenses.
Keep the money separate from your everyday spending balance if possible. A separate savings account or suitable savings wallet can make it easier to track your progress.
However, do not force yourself to save money you need for food, essential medication, rent, or other urgent obligations. If your expenses exceed your income, addressing that shortfall comes first.
Your initial goal might be to build a small emergency fund that can help cover an unexpected transport expense, household repair, or essential bill without borrowing.
Every amount saved can help, but your progress will depend on your income, expenses, and circumstances.
5. Look for Ways to Increase Your Income
Sometimes, cutting expenses is not enough. If you have already reduced unnecessary spending and still cannot cover your essential needs, increasing your income may be necessary.
Consider opportunities that fit your skills, schedule, and available resources.
For example, you could explore:
- Freelance writing, editing, or proofreading.
- Virtual assistance or administrative support.
- Online tutoring or teaching.
- Selling digital products or handmade items.
- Offering a service to people or businesses in your community.
If you have a laptop and internet access, you can begin by identifying one service you can offer, creating a few work samples, and contacting potential clients.
You do not need to pursue every opportunity. Start with something you can realistically manage alongside your existing responsibilities.
Be cautious of online opportunities that promise guaranteed income, demand large upfront payments, or require you to recruit others before you can earn. Research opportunities carefully before sharing personal information or paying fees.
6. Plan for Bills Before They Become Urgent
Unexpected expenses can disrupt even a carefully planned budget. While you cannot predict everything, you can prepare for some costs.
Write down upcoming bills, renewal dates, school expenses, annual payments, and other predictable commitments. If an expense is due in several months, estimate how much you would need to set aside each week or month, provided your budget allows it.
You can also set reminders on your phone or use a free calendar app to avoid missing payment dates.
If you know you cannot meet a payment deadline, contact the relevant provider or creditor early to ask whether a payment arrangement is available. Ignoring the problem may leave you with fewer options.
7. Review Your Progress Every Week
You do not need to monitor every transaction all day. Set aside 10–15 minutes each week to review your finances.
Ask yourself:
- What did I spend more on than expected?
- Did I avoid any unnecessary purchases?
- Are there upcoming bills I need to prepare for?
- Is there one change I can make next week?
This simple routine helps you identify patterns and adjust your budget before small problems become bigger ones.
Remember that some months will be more expensive than others. An unexpected bill does not mean you have failed. Review what happened, make adjustments where possible, and continue.
Final Thoughts
Saving money when your income is not enough requires more than discipline. It requires understanding your financial situation, prioritizing essential expenses, and finding realistic ways to improve your circumstances.
Start by tracking your spending, reducing costs that are not essential, and saving small amounts when you can. If your income still cannot cover your basic needs, consider practical ways to earn more and seek appropriate support when available.
You do not have to make every change today. Choose one manageable step and build from there.
The goal is not to save the most money immediately. It is to make your money work as well as possible while building a more stable financial future.